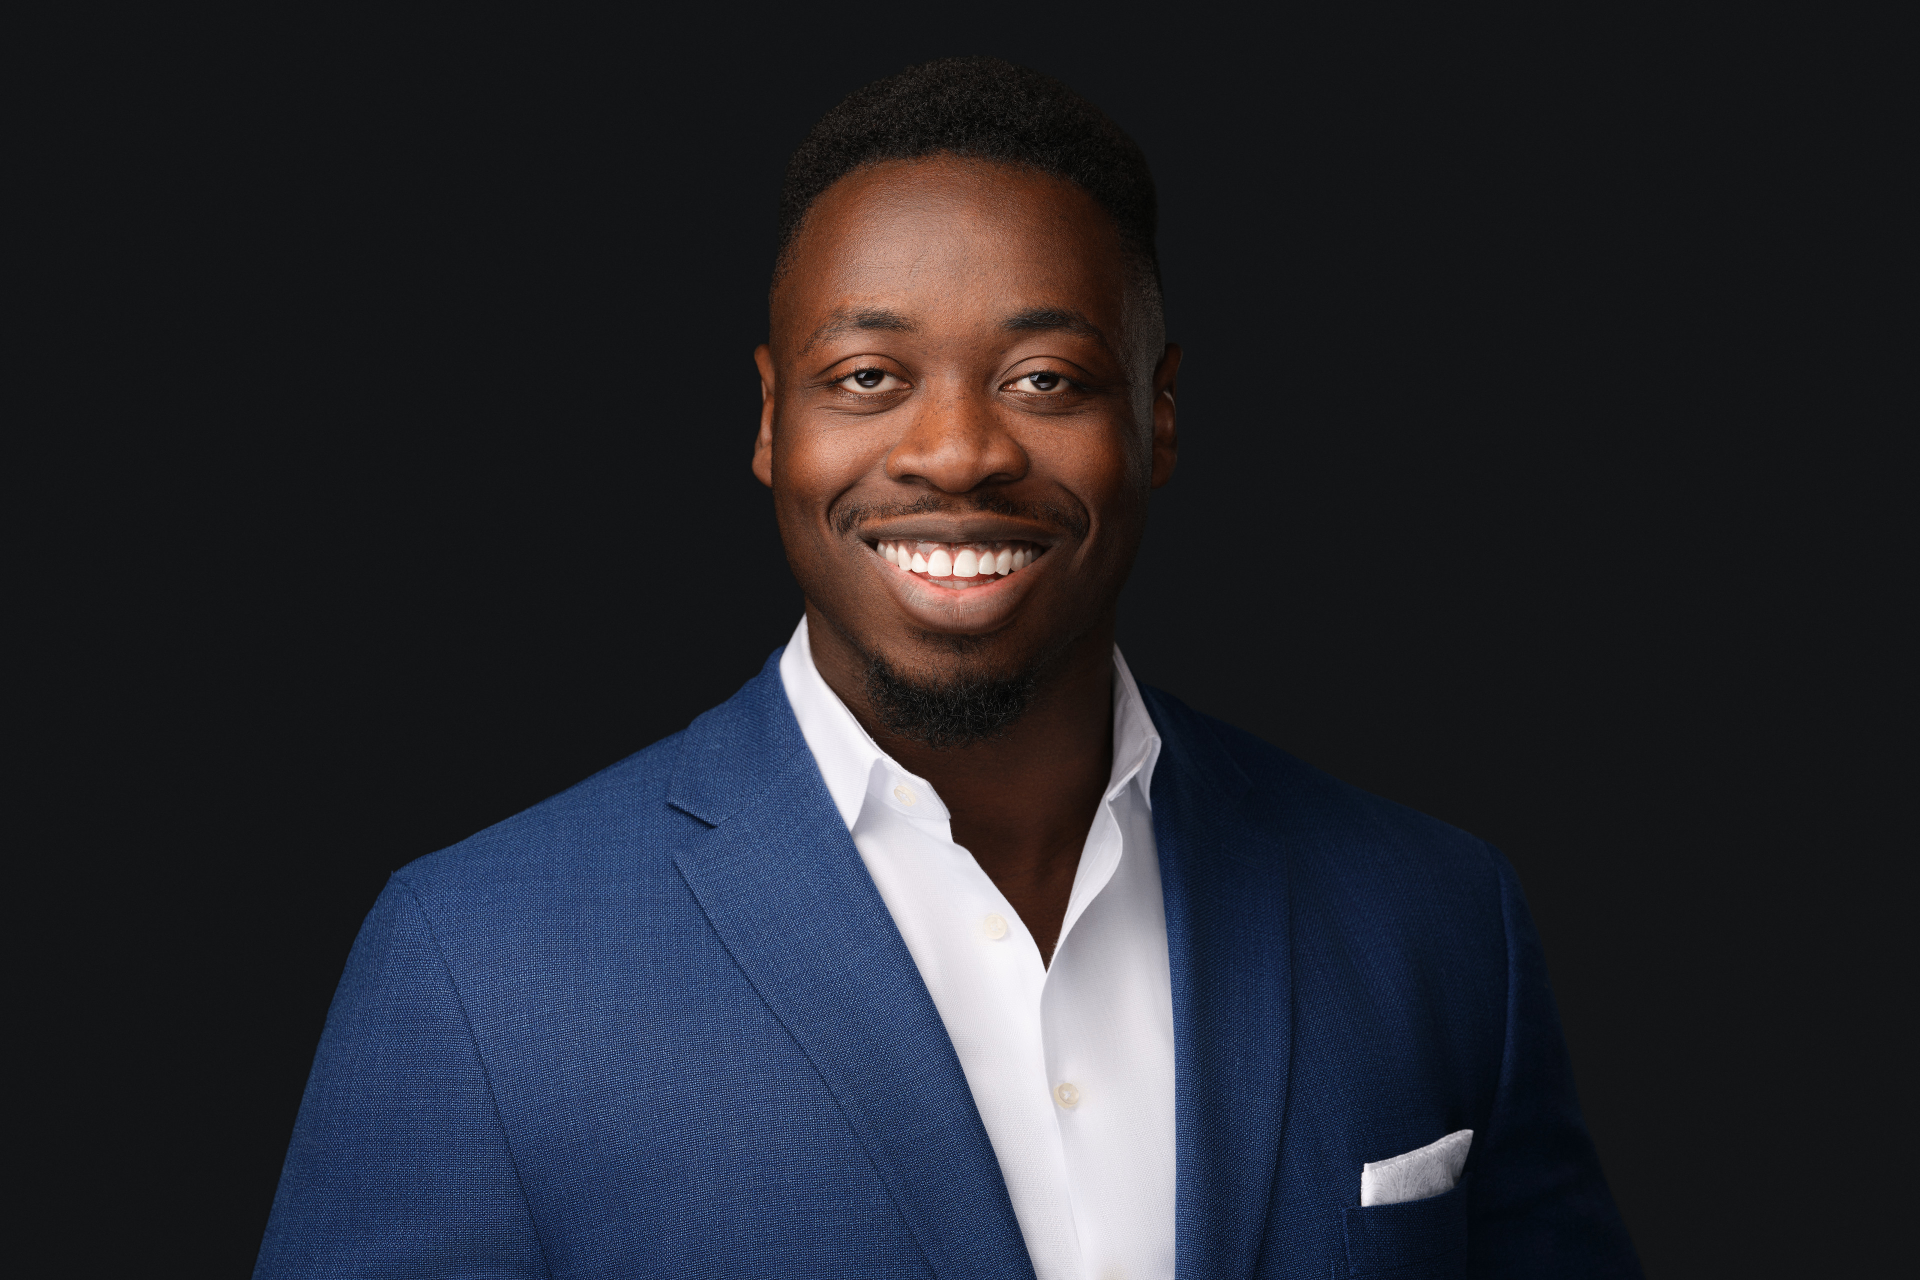
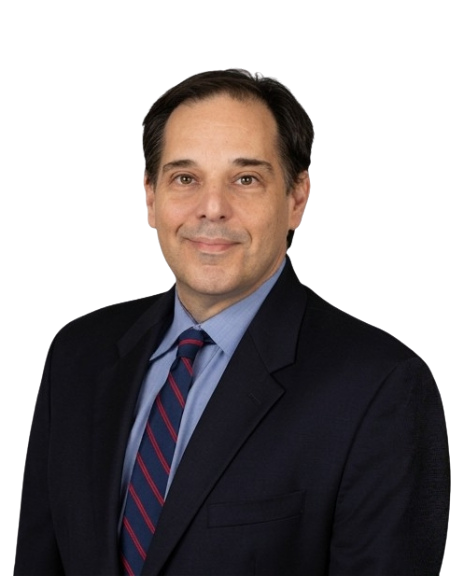
Natu Myers
Hi everybody, this is Natu back with the Raises.com Top Capital Raiser Show, and today I'm joined by a very intelligent guest. Our guest today is Steven Wallace. Steven is a legal expert and attorney. He advises and counsels clients on bankruptcy law, real estate law, business law, and securities law. He's been doing so for over 20 years, and Steven brings a wealth of information when it comes to being in compliance, making sure your documents are structured properly, and following the law as it relates to doing deals, starting a business, and everything in between. Steven, it's fantastic to meet you today.
Steven Wallace
Thank you so much for the opportunity. I really appreciate you having me as a guest on your podcast.
Natu Myers
No problem. Doing the research for this, you had a really interesting background. You founded Wallace Law and you operate in several cities. Can you walk me through your background, how you got into law, and how Wallace Law came to be?
Steven Wallace
Sure. I'm licensed to practice in three states: New York, Florida, and Texas. I grew up in New York and went to law school at Syracuse University, which is almost Canada, the northern part of New York. When I was in law school I was molded into the practice areas I practice now. My first year I interned with a bankruptcy lawyer, and she taught me how to do everything. I've applied that since, and one of the benefits is that I have a good-economy and a bad-economy practice.
Steven Wallace
My bad-economy practice is bankruptcy, and in certain markets in Texas and in South Florida we're in the bad economy right now. My phone is ringing off the hook for businesses and individuals looking to get protection under the bankruptcy code and restructure or discharge debts. My second year, and throughout my career, I worked at a large firm in Syracuse, a large firm in Dallas in the corporate securities section, and later in South Florida in the real estate and banking section. That's my good-economy practice.
Steven Wallace
I'm a Florida Bar board-certified real estate attorney. Only about 5% of Florida lawyers, around 450 of us, hold that certification, and the Florida Bar allows us to say we are experts. I also have a very vibrant practice in Dallas and Houston. I have offices in South Florida and Dallas, and we just opened a Houston office. We're busy. One of the things we pride ourselves on is that we're business-focused. I'm a business owner first and a lawyer second. A lot of lawyers get caught in the weeds and can't get out of their own way, and you hear it from a lot of business folks: lawyers kill deals. I pride myself on being a dealmaker, not a deal-breaker.
Natu Myers
Everybody listening, it's almost a cliché at this point that lawyers kill deals, but the types of people we bring on, including Steven especially, enable people. Syracuse holds a close place to my heart, my grandmother graduated from there back in the seventies. So, what approach do you take at Wallace Law? Is there something from your education, or a personality trait, that brought you into law, and what's unique about your firm?
Steven Wallace
For me, Syracuse is where I grew up. It's a small town, a blue-collar area, and I'm the first one in my family to graduate college, let alone law school. I tell my kids this all the time: when I graduated from Syracuse University, my grandfather had a clothing store selling Syracuse merchandise right off campus. He passed away before I attended, but my graduating from Syracuse was a really big deal for my whole extended family. I understand where I come from, and that gives me a unique perspective on how a lot of folks operate, and real compassion and empathy for people.
Steven Wallace
It comes into play a lot in my bankruptcy and restructuring practice, because most people who come to me are in some level of failure. They may have sickness, they may have lost a job, lost a spouse, lost a family member. I enjoy working with those clients because I'm very solution-oriented. I use that in my restructuring practice and in my business and real estate practice. I love to solve problems. As we talked about earlier, I'm not the kind of lawyer who says no, no, no. A lot of lawyers want to find a reason to say no, to protect you from yourself. We're getting to the yes.
Natu Myers
I love that. There are definitely some lawyers who are more positive, empowering, and business-forward, and then some who are almost draconian. It's really fascinating, the different types of personalities in this business. So let's say somebody comes to you who wants to raise money for their business. They don't know anything about Regulation D, what a 506(b) or 506(c) is, what the Investment Company Act or blue-sky laws are. How do you set expectations on what they're going to pay and what's going on, and make sure you're not selling them something they don't need? How do you walk through that process and build trust?
Steven Wallace
Sure. The first question I always ask, and it's in all aspects of my practice, is: what are your goals? What do you want to achieve? If somebody says, I'm looking to raise $5 million because I want to buy this apartment building, and I've got some sponsors and limited partners that will invest, but we need money to bridge the gap so we can get senior or mezzanine financing depending on the capital stack, then we start there. The purpose of the securities laws is really to protect the investor, not the company. We have to make sure they understand that first, and second, that when they're looking to raise capital they stay within the guidelines.
Steven Wallace
For example, in a Reg D offering, for the most part you only solicit accredited investors, with some exceptions for non-accredited investors. The other thing is: how are you going to raise it? What medium? When 506(c) came into play it opened things up, because before that there were a lot of restrictions on how you could solicit funds. With 506(c) we now have more opportunities through a variety of mediums and technology. Then a lot of people also got excited about crowdfunding, Reg CF. I just need to understand from the client what they're hoping to achieve, and then I find a way, if one exists, to allow them to reach their goals within the regulatory framework.
Natu Myers
That's amazing. You start with the goal in mind and reverse-engineer from there. Dealing with the law, it sometimes seems like lawyers fight each other. Some lawyers work for the SEC, or in Canada for the OSC, then you have compliance lawyers, lawyers retained by firms, and lawyers retained by issuers. Sometimes they disagree and almost fight, because both want to get their job done and the jobs contradict. What happens when two lawyers disagree on something? How do you know who's right, and how do you navigate that?
Steven Wallace
Ultimately, if nobody can agree and we need a determination of who's right, a judge or a jury makes that determination. Everybody has different styles. There are lawyers who are fast and loose and just want to get the deal done without consequences. It goes back to what the client's goals are. I'm mostly a transactional attorney, with a lot of vast experience in very complicated business and real estate transactions, and at times those go to bankruptcy and we have clients buying out of bankruptcy, or I represent a debtor selling property out of bankruptcy. I look at things from a different lens, as a business owner: when things go awry, we have to go to court. It's not a Hunger Games scenario where someone wants to duel to the death.
Steven Wallace
I look at litigation or disputes as an opportunity. When there's no meeting of the minds, it's a tool to renegotiate the transaction and ultimately determine your client's goals or get fair value. I've dealt with regulation attorneys representing governmental entities, and often they're fixated on whatever the edict is from the department or agency. That depends on the philosophy of whoever is in political power, and that determines the level of enforcement and which new rules come into play. I'm not going to dive into the nitty-gritty of politics, but in securities, politics really comes into play. Depending on which party is in charge it will tilt restrictive on business or more open to business.
Steven Wallace
At the end of the day, issuers and businesses hire lawyers like me to understand the regulations currently in place and to maximize exemptions or the idiosyncrasies and inefficiencies in the rules to our client's advantage while staying within the framework. In U.S. securities transactions, what we have is the 1933 Act, the 1934 Act, the 1940 Act, the regulations, case law, and SEC no-action letters. The no-action letters are the ones that tell us: here's a fact pattern, compare it to ours, and determine what we can and can't do. Lawyers are often governed by their clients. When I worked at larger firms I felt a lot of pressure because we had large institutional clients we always had to keep happy. I'd sometimes have philosophical or fundamental arguments with management, because at the end of the day my law license is a golden ticket to make money the rest of my life and I don't want to jeopardize that, my integrity, or my ethics. That's why I'm a lot more comfortable running my own small firm.
Natu Myers
That's so real and so powerful. There's a lot there. Let me approach it with this vector: when clients work with you, you have a close relationship with them. Some clients are urgent. Maybe the SEC sent them a letter and they got scared, or somebody sent them a legal threat, or they're about to close a deal. The challenge is that when people aren't urgent, they may not be ready to engage, but when they're super urgent and almost desperate, their expectations are misaligned. How do you set expectations? Because if someone is trying to work with you to close a deal, there's no guarantee of particular results, it's really to minimize risks.
Steven Wallace
Sure. One of the things I always tell clients at the start of a representation, on the transactional side, business side, or real estate side: I'm here to protect you from yourself. The goal is to get the transaction done ideally and protect you and minimize your risks. People ask, well, what do you think is going to happen? My retort: if I could predict the future I wouldn't be a lawyer, I'd be at the horse track or the casino. We have no idea what's going to happen. We use the information we have at the start and I use that to protect their interests as much as possible.
Steven Wallace
The one thing I can't protect against is human nature. If you're dealing with somebody who isn't of the same business values or ethics as you, you always have to worry. I have a transaction right now where my client is buying a property from a lender who took it back from foreclosure, with a receiver on it. There's a lot of hair on it, and it's in downtown Miami, so multiply that by a thousand. We researched the party and found that the principals went to federal prison for securities fraud. I had a heart-to-heart with my client and said: no matter what, this transaction in one way or another is going to end up in court. Are you prepared to handle it that way? Because at the end of the day, if things go awry, the person with the most money will lawyer you and paper you into submission.
Steven Wallace
As a consultant, you can relate. The most successful people in our industry are the ones who manage expectations and communicate, no matter if things go well or not. I'm always working on my communication skills. You could be the smartest lawyer in the world, but if you're terrible at communicating, you won't be successful or have clients. I always get a pit in the bottom of my stomach when I have to deliver bad news, oh, we lost this case, or the other side won't agree to our position. Sometimes we have triage and damage control.
Steven Wallace
There are clients I'll never take on. If somebody calls and says, I want justice, never take that client. Number two: somebody who says, I need it right now, I need it now, I have something coming up tomorrow, you have to get it done. Often it's the boy who cried wolf. These people don't respect your time or you as an attorney. We have to be successful, and to be successful you have to have multiple clients. I'm always training my staff: we have to determine what is most urgent and what is most profitable. A lot of times I spend my day on things that aren't profitable. Attorneys are paid hourly, and there are only 24 hours in a day, so for all intents and purposes our income is capped. One benefit: I always try to develop different streams of income. In certain states, especially in Florida, we also serve as title agents, so we have an extra stream of revenue because we receive a commission from the title underwriter.
Steven Wallace
Being an attorney is a grind, there's no doubt. I love it because I love the deals, I love the excitement, I love helping people, I like getting people from point A to point B. That road may be rocky, it may take a lot of turns, we may take a couple steps backwards, but I love finishing it, I love being a closer. I like the movie Glengarry Glen Ross. Coffee is for closers. I have that shirt I wear to the gym all the time.
Natu Myers
Always be closing. This watch is worth more than your car. If you ever hear a lawyer talk about Glengarry Glen Ross, you know he's a real dealmaker. You mentioned the title-agent system. People can probably pick up from how you communicate that you're a dealmaker, that you're incentivized, that you love working with clients to close deals. But when people look at it, aren't they just thinking, hey, we retain this guy for X amount, we put money in escrow, and that's it? How can people see you as incentivized to close the deal, beyond just the good word and reputation? Some might say, well, an investment banker gets a commission on the money raised. How do you handle that objection?
Steven Wallace
A lot of business owners and investors look at lawyers as a line item on the spreadsheet, an expense. One of the things that separates lawyers is how much value do you create. I pride myself, and you can interview a room full of my clients, on the value I provide because I'm not just a lawyer or an hourly grinder. I'm a trusted member of the team. I provide my legal input, my protections, all the disclosures to make sure on the securities side you're not going to jail. The biggest thing is you don't want SEC enforcement coming in like in Wall Street, breaking your door down, with Charlie Sheen getting locked up in the back of a police car.
Steven Wallace
I'm also a sounding board. I'm somebody who says, well, what do you think? On the title insurance side I only get compensated if the transaction closes. So I'm a team member working with you to close the transaction or, if it doesn't close, to protect you on the downside. I don't know if I could afford to retain myself, but there is value provided. I'm a small firm, but on almost every transaction I'm on the other side with an Am Law 100, 200, or 50 firm, and I leverage technology. We could have a whole podcast on how technology has changed business. Instead of going to the same studio to record a podcast, we do this virtually. But technology also usurps our time. Clients can reach me 24 hours a day, by text or email.
Steven Wallace
The downside, from a mental health standpoint, is that you have to set boundaries in your business and your personal life. As a young attorney working at a large firm in downtown Dallas doing corporate securities, I pulled all-nighters most of the time. There were nights we'd stay at the printer to get the book out so our clients could go public. I have a podcast called Attorneys Are Human Too, on Apple, Spotify, wherever you get your podcasts, where we talk a lot about the human side of practicing law. Law school doesn't equip you for the demands. Clients come to us in their absolute worst hour, or with a transaction that will create generational wealth for them. I don't take any of it lightly, but you have to take steps away too.
Steven Wallace
A benefit I see in the generation under me, probably one or two generations under me, is that they value self-care and mental health. Practicing law is a grind. I've been an attorney since I was 26, I'm in my approaching 30th year of practice, and I'm still a young guy. I'll probably be practicing law 50 or 60 years, God willing, but I don't want to be the lawyer who dies at his desk. That's the other joke. I have a lot of other interests: I do a lot with the community, I help out with youth, I've done some things as a community organizer in a political role. There's a lot of different things I do, and I have a lot of varied interests now. When I first started, I was just grinding.
Natu Myers
You mentioned how people don't set boundaries and the clients you work with pass certain filters. Even in people who want to raise capital, you can't raise millions if you have a negative five-figure net worth and you're 25 years old. We have to let some people go.
Steven Wallace
Or they don't have a feasible business idea. That's a challenge we always have. How come I'm not raising 20 million? Look at your balance sheet, look at your projections, look at your model. I often have uncomfortable conversations and just give them advice. It goes back to managing expectations and communication. The city wasn't built in a day. You have to look at yourself.
Steven Wallace
I've seen different market cycles. When I was in Dallas at the big firm it was during the dot-com boom. There were ridiculous companies. As long as they put a .com at the end, people threw money at them, and the burn rate was out of control. Then I practiced in South Florida during the Great Recession. I was doing residential closings through my own title company. I'd do million-dollar refinances for a teacher making 30,000 a year, with payments fixed for two years that would then float on indices that no longer exist. Or interest-only loans, or negative amortization loans. I've seen a lot of things go up and a lot of things go down, and that makes me a smarter, better lawyer because I can give advice on it.
Steven Wallace
One thing we can't control is economic policy. We go to the polls and vote in whoever we think is best, but it's not our sole decision. We can't control politics. In the U.S. we're experiencing conflicts right now with foreign bodies, and that kills us. I have a bunch of clients who, because of economic or political decisions, are now in bankruptcy court struggling to save their businesses. I like to provide an entire view: we see a policy coming, we have to brace. We can't foresee the future, but we can take the data and anticipate what's going to happen in the market so we're not behind the curve.
Natu Myers
It's all timing. You can be the smartest person in the world and have horrible timing, and you're in financial ruin.
Steven Wallace
One of my biggest real estate development clients always says: it's better to be lucky than good. And if everyone could do it, we wouldn't be successful. When I say lucky, I don't mean a coin flip. I mean using the information you have to make a smart decision. We're always result-oriented. If there's a success it was a great decision, if it fails it was a poor decision. But look at the process. You could have the best process in the world and fail, or the worst process in the world and succeed. It only takes one success to create generational wealth, the challenge is making good decisions to preserve it. I've seen people make more money than all of us collectively in our lifetimes and then make a poor decision and lose it all.
Natu Myers
Are you saying it's better to focus on good inputs and accept the outputs are sometimes out of our control?
Steven Wallace
Almost the opposite. You're judged by the output, by success. You could have the worst input and the output is amazing, or the best processes and be a failure. It's skill, luck, and timing. Once you reach it, you make good decisions to maintain and grow. As a business owner I'm always making decisions, some successful, some not. I'm smart enough to know that if something isn't working I'll cut bait and make a new decision. A lot of it for me is marketing, getting the word out, because there are a lot of lawyers in Florida, Texas, and New York. We could fill the SkyDome with lawyers.
Natu Myers
When clients have success and they make that lucky decision, more money flows in and they connect the positive outcome to you and the relationship grows. Is that what you see?
Steven Wallace
Yes. My high-ticket clients have been with me for a very long time. We've been through good times and bad. They know I'm always loyal. Some larger firms, if you're having difficulty paying the bills, cut you. I understand, going back to the first question, that I grew up blue-collar. My family was blue-collar, and I'm as white-collar as can be now, I can barely change my own oil, but I appreciate the struggle. I know there is no way I'm going back to that struggle. I'm going to work hard, I'm going to grind. I understand human nature, failure, and success. There's a great book called The Art of the Comeback. It wasn't very successful, but it's one of my favorites because it shows how to work through adversity. I have a lot more respect for somebody who's worked hard and overcome obstacles than someone with a pedigree who hasn't understood the struggle. My kids don't struggle. I have them focus on school and sports. That's all they need. When I was growing up there were other things to worry about. That makes me who I am, a hard worker who appreciates everyone's unique qualities. We all have the same goal: to be successful, to be in the top 0.01%.
Natu Myers
How do you keep your kids grounded so they don't become too soft?
Steven Wallace
I'm strict but compassionate and empathetic. I created Wallace Law, God willing, as a legacy for them. I have two children. Sometimes I'll bring them to a hearing or have them in the car when I'm talking to clients. They don't hear the substance, but they hear how I treat people. I'm a lecturer, I like to give examples. The lesson I instill: no matter who it is, you don't want to be that person who treats a server or an Uber driver as less. I treat everyone with respect. Everybody has a story and dignity. That's what I instill in my children, in my staff, and in my clients. They don't always listen, because I have clients from all walks of life.
Natu Myers
Let's look at the future. There's a lot of regulatory change. Gary Gensler is out, the Reg CF platforms got the hammer at one point, and there were times when DOGE-style talk said too much regulation. Securities is literally all about regulation. Where is everything going with bankruptcy law, securities law? What should people expect from you and from the markets in the future?
Steven Wallace
Let's talk about the corporate securities market because that's a big interest to your listeners. It really depends on which administration is in play. I'm not going to take a side, I'm just speaking on the U.S. The current administration's goal is the least amount of regulation within the framework that they can get, which for businesses is great, for consumers it may or may not be. The prior administration had volumes of regulation, not just in corporate securities but across the board.
Steven Wallace
There's a big trade-off. This is where my political science degree comes in. Lack of regulation is great for business, but often the consumer can be harmed. That's why corporate securities and securities regulation exist. The 1933 Act came in because after the Great Depression a lot of businesses were taking advantage of people, raising capital, and stealing money. My goal is to make sure my corporate clients raising capital don't have enforcement actions and don't go to jail. That's why you hire a lawyer. You're not a true deal lawyer unless the FBI calls you once every five years to inquire about your clients.
Natu Myers
Even in real estate, some guests say tenant laws are too lax in certain states. In Canada some have joked that Canada is a state. Tenant laws here are too lax and securities laws are too strict. There's always a trade-off between the consumer or tenant and the business.
Steven Wallace
I totally agree, because we're the ones paying the bills to stay compliant. Something important for your listeners: it's a major cost to comply with the securities laws. I always have clients who say, I want to go public, I want my IPO, I want my S-1. Do you understand how expensive it is to maintain a public company? Filing the S-1 is hundreds of thousands of dollars, and then under the 1934 Act you file quarterly and annual reports, so you have a humongous bill from your accountants and your securities lawyers. If you're going public, you have to understand the cost of maintaining it.
Steven Wallace
We see many smaller issuers that go public and then can't even afford to maintain compliance. There's a lot of talk in the small-cap market: I want to do a reverse merger, take my body shop public, because then I have the ability to raise all this money. That's true, but the cost of that privilege is astronomical.
Natu Myers
Even the OTC is still expensive. Are those the same prices as the NASDAQ?
Steven Wallace
On the OTC you don't have as big of a market, but you still have all the requirements under the 1934 Act, which are the same as if you're on the New York Stock Exchange. It's expensive. People need to factor that in. On the flip side, if you get a private equity firm to invest, the cost of funds is very high and you can lose operational control. There's a lot to keep in mind when raising capital, not just the monetary cost, but the freedom and operational cost. As a public company you're answering to shareholders, and how many times does a founder get pushed out even before the company goes public? There's a lot to keep in mind.
Natu Myers
People want the benefit without the sacrifice. Steven, this has been really refreshing. Let's leave a message from you to the listeners. What's one thing you'd like them to take home?
Steven Wallace
Sure. What you want to see is that Steve Wallace is not only a smart attorney, technically a good attorney, but he understands the market. He understands the needs of a business owner or an individual going through a beta company, a generational wealth opportunity, or saving themselves from financial calamity. He's not only a technical guy, he's a strategist, and he's compassionate. He understands you and he wants to work with you to achieve your goals.
Natu Myers
How can people get in touch?
Steven Wallace
We're all over the place. We have an informative YouTube channel, Wallace Law. We're on Instagram with a few accounts: Wallace Law Florida for Florida clients, Wallace Texas Law for Dallas clients, and Wallace Bankruptcy Law for bankruptcy clients. Online, we're wallacelawtx.com for our Texas clients and wallacelawfl.com for our Florida clients. And if you like to hear me talk, you can listen to our podcast, Attorneys Are Human Too, on Apple, Spotify, or wherever you get your podcasts. I'd love to have you on for a future episode.
Natu Myers
Amazing. All that information will be in the show notes. Steven is the real deal, a real lawyer who does deals. I encourage you to check him out. Steven, awesome to have you.
Steven Wallace
Truly a pleasure, sir.